Easy RV Loans: What to Check Before You Sign

Stop shopping for the smallest monthly payment. That's the most popular advice about easy RV loans, and it's also the advice that puts Utah buyers underwater on a trailer they can't afford to store, insure, or tow to Jordanelle.
An easy RV loan isn't the one approved in an afternoon. It's the one you can compare line by line, APR, finance charge, and total of payments, and still afford after winter storage, fuel over Parleys Summit, and a pre-season service visit. Our team at Motor Sportsland would rather lose a same-day signature than watch a family learn that lesson in January.
Why a Fast Yes Is Not an Easy RV Loan
A Salt Lake family finds a bunkhouse travel trailer on Saturday. The advertised payment fits the number in their heads, they sign that afternoon, and they celebrate on the drive home. Then the full-coverage insurance quote arrives, followed by Wasatch winter storage and the fuel bill from their first Bear Lake trip.
None of those costs appeared in the payment they approved. That's the trap, and speed built it.
Our test: If you can't compare the APR, finance charge, and total of payments against at least two other written offers, the loan isn't easy yet. It's just fast.
Borrowing most of the price is common. A nationwide survey of major financial institutions estimated that borrowers financed an average of 81.6% of an RV's purchase price, and 33.4% of RV loans financed used units. At that loan-to-price level, the rate and the term have much greater impact than the monthly payment. Taxes, fees, and the down payment all affect the true cost, and none of them show up in the figure quoted across the desk on Saturday.
A pre-qualification earns its keep here. It lets you explore financing options with no commitment before you file a full credit application, so you can hold terms next to a bank or credit union quote instead of taking the afternoon's first answer. Comparing only counts on matched fields: same term, same down payment, same financed amount. A lower payment stretched over more months is a longer loan wearing a friendly face.
Work in this order. Fix your credit file and paperwork, price the Utah cost stack, run the term math, shop inside one window, then apply a keep-or-walk rule. Our team can put a written offer beside your outside quotes at the Motor Sportsland showroom so you're judging the same fields.
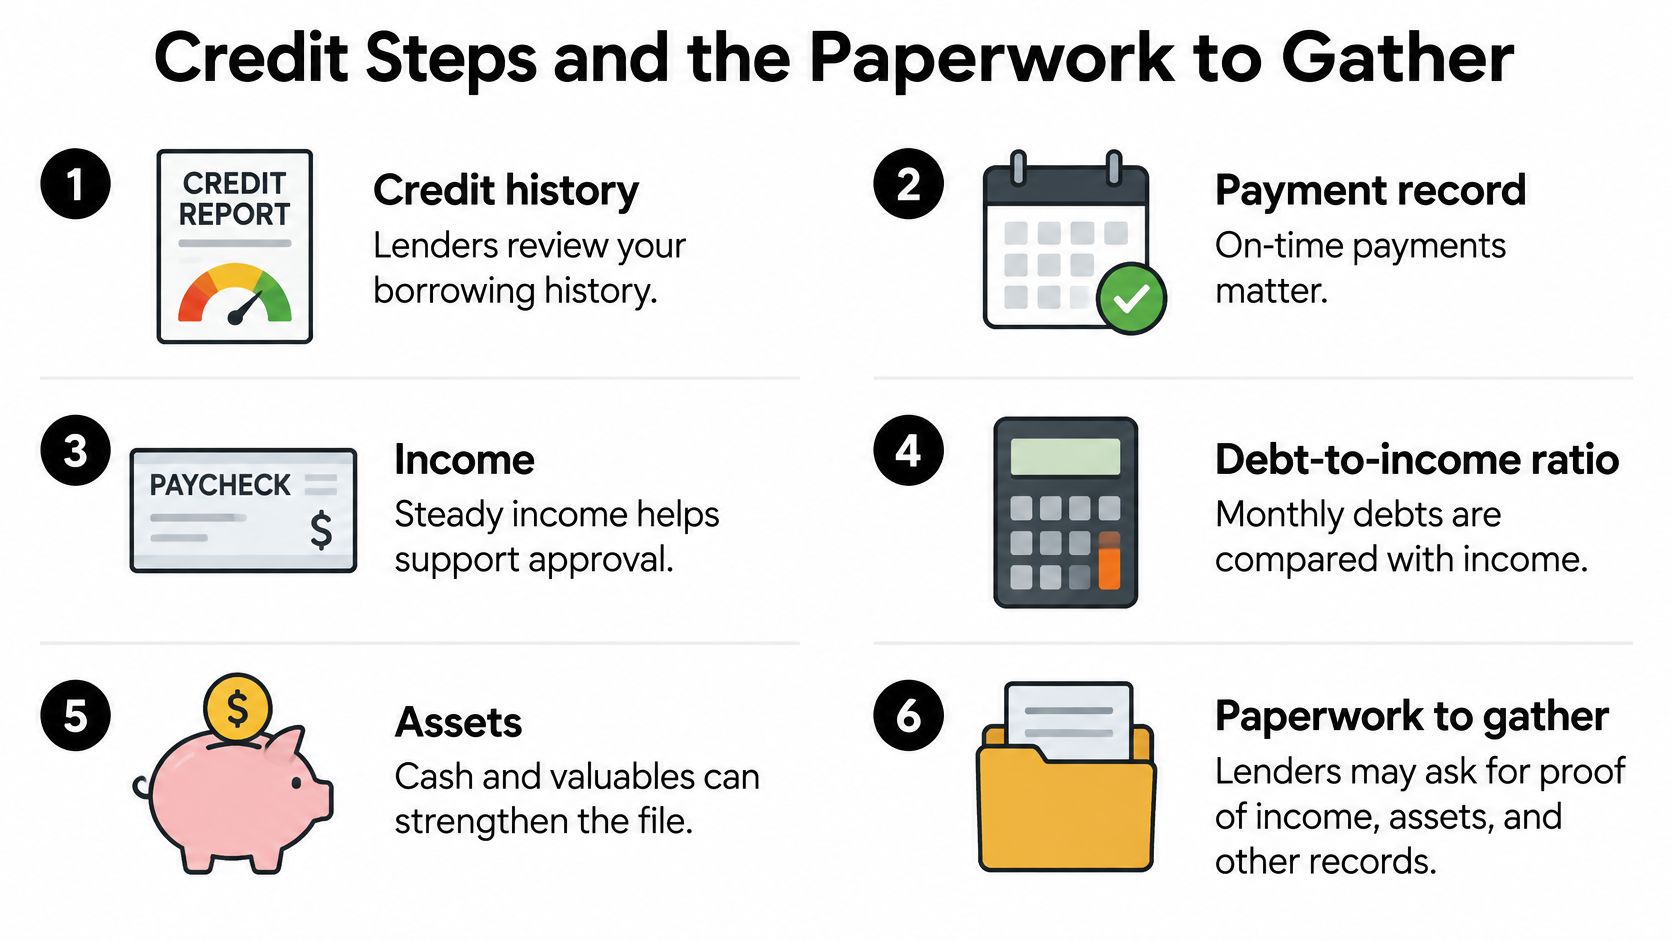
Credit Steps and the Paperwork to Gather
Your credit score is one line of the file, not the whole file. A current Truist lender disclosure for RV loans states that secured RV loans may have no fixed minimum score, with lenders weighing credit history, payment record, income, debt-to-income ratio, assets, and the planned down payment. Stronger files show several years of history, varied account types, stable income, liquid or investment assets, and few or no late payments.
You can move most of those levers in a single week, before anyone pulls your credit.
Four Prep Moves Before You Apply
- Order your credit reports first. Dispute errors before the first application, not after a lender prices you on bad data.
- Lower revolving balances. Pay cards down before the pull so utilization and minimum payments don't inflate your debt-to-income ratio.
- Document twelve months of income. Don't present your best month. If your pay swings with ski season, construction, or summer guiding, let the lender size the loan on the average.
- Write down your down payment. Save toward it and commit to a number you won't raid later for gear.
Build the Packet in Order
Walk in with these seven items and you remove most delays:
- Government ID and proof of address: Bring both, current and matching.
- Income proof: Recent pay stubs, or a full year of tax returns if you're self-employed or seasonal.
- Bank statements: Show the down payment and the reserve you'll keep after closing.
- Debt list with minimum payments: Cards, auto loans, student loans, everything.
- Trade title or payoff letter: Get the payoff in writing if you still owe on a trade.
- Insurance quote: Price full coverage on the actual unit, not a guess.
- RV details: Year, VIN, and selling price for the specific trailer, fifth wheel, or motorhome.
This packet doubles as your worksheet. When every lender sees the same income, the same debts, and the same down payment, the offers come back comparable line by line. That's what easy looks like.
Keep two tools separate. We offer a pre-qualification with no commitment for shopping, and a full credit application for when you're ready to move forward. Our guide to RV financing pre-approval walks through that split.
A clean file speeds the yes. It doesn't set the payment your household should accept.
Utah Costs That Change a Comfortable Payment
A loan quote shows principal and interest. Ownership sends you six more bills.
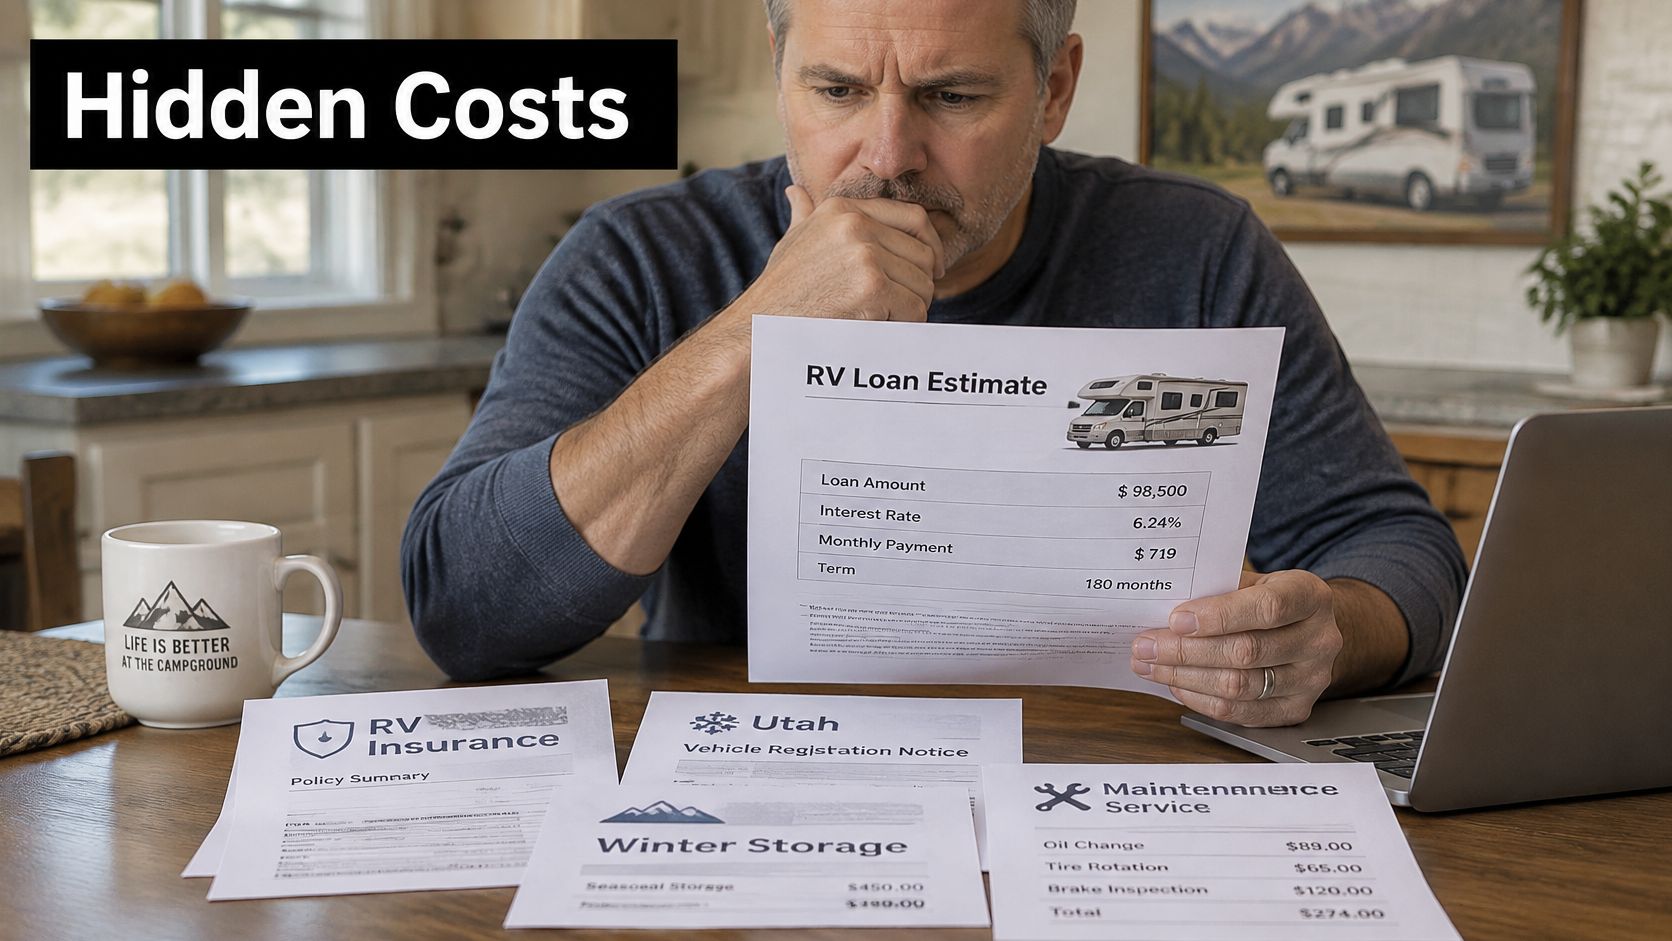
Fill in every line below before you call any approval easy. Price them for Utah, not for a generic national average.
| Cost line | Notes |
|---|---|
| Principal and interest | From the written offer's payment |
| Full-coverage insurance | Get a quote before signing |
| Utah registration | Confirm the amount with the state |
| Winter storage | Price by month for Wasatch winters |
| Pre-trip maintenance | Budget a service visit before each season |
| Fuel for tow vehicle or motorhome | Estimate from your typical trips |
| Campsite fees | Jordanelle, Bear Lake, and other sites |
| Emergency reserve | Several loan payments plus insurance and maintenance |
A lower price on a used travel trailer, bunkhouse, fifth wheel, or toy hauler can still hide costs. A weight-distribution hitch, brake controller, tires near the end of their life, or a first-season roof reseal can erase the savings fast. Get a pre-purchase inspection and price towing equipment and payload limits into the stack before you finance, not after.
This short walk-through shows how those extra lines change a payment that looked comfortable at the desk.
Keep an emergency reserve covering several loan payments plus insurance and maintenance. Confirm the first due date, set autopay, and name a backup account.
Use the broader auto market only as a warning light. The Federal Reserve's New York Fed and Equifax credit panel analysis defines delinquency as a payment at least 30 days past due, excluding severely derogatory balances, and put the seasonally adjusted auto-loan delinquency rate at 3.8066% in the second quarter of 2024, up from 2.9392% in the third quarter of 2022. That dataset doesn't measure RV defaults. It does show what happens when households approve payments with no cushion.
Match the Move to Your Credit Tier
- Excellent credit: Take the shorter term if the payment still clears the full stack.
- Fair credit: Raise the down payment before you lengthen the term.
- Challenged credit: Shop a smaller used trailer or folding camper instead of forcing a payment that only works on paper.
The lender's maximum is not your household budget.
Term Length and What You Really Repay
Start with the math, not the opinion. In a Consumer Financial Protection Bureau comparison of a $20,000 loan at 4.75% APR, a 36-month term costs $597 per month and $1,498 in total interest, while a 72-month term lowers the payment to $320 but raises total interest to $3,024. The longer option costs more than twice as much interest for the same loan and the same rate.
| Term | Monthly payment | Total interest | What it means |
|---|---|---|---|
| 36 months | $597 | $1,498 | Harder payment, less interest |
| 72 months | $320 | $3,024 | Easier payment, more than double the interest |
That example uses an auto loan figure, and the trade-off works the same way on easy RV loans. Stretching the term cuts the payment today. It also slows how fast your balance falls, which raises the risk that the RV loses value faster than you build equity. If you trade, sell, or total the unit early, you can owe more than it's worth.
Test every term against how long you'll keep the RV and how that model holds value. A bunkhouse your kids will outgrow in four seasons shouldn't carry a payoff schedule built for a decade of use.
Learn the Three-Field Scan
Read every written offer in this order:
- APR: The yearly cost of credit including mandatory fees. It's broader than the advertised note rate, so it's the number you compare across lenders.
- Finance charge: The total interest and certain fees you'll pay over the life of the loan.
- Total of payments: Principal plus finance charges. This is every dollar you'll send the lender if you ride the loan to the end.
Rank offers by APR and total of payments first. Use the monthly payment only as a ceiling your household has already cleared against the cost stack.
If two quotes show the same payment, keep the one with the lower total of payments. The other lender is charging you more for the same monthly comfort.
Confirm three more fields before you sign. Check the required down payment, the trade-in credit, and any optional products folded into the amount financed, such as service contracts or protection plans. Optional means optional. If you don't want it, have it removed and get the quote reprinted.
Two Rules That Prevent Most Regret
First, if a unit only fits on the longest term offered, shop a lower price instead of stretching the loan. You're not solving an affordability problem, you're postponing it and paying interest for the delay.
Second, ignore an advertised easy rate until it's your rate in writing. Credit history, income, debts, down payment, term, loan amount, and new versus used all change the final APR. A headline rate built for a top-tier buyer on a new motorhome tells a fair-credit buyer shopping a used toy hauler almost nothing.
Price the term before you fall for the floorplan. Floorplans don't send monthly statements.
How to Compare Offers in One Shopping Window
A loan is only easy if you can audit it line by line and still afford the RV after Utah ownership costs. Run these steps in order. Do not treat the first dealer quote as final, ours included.
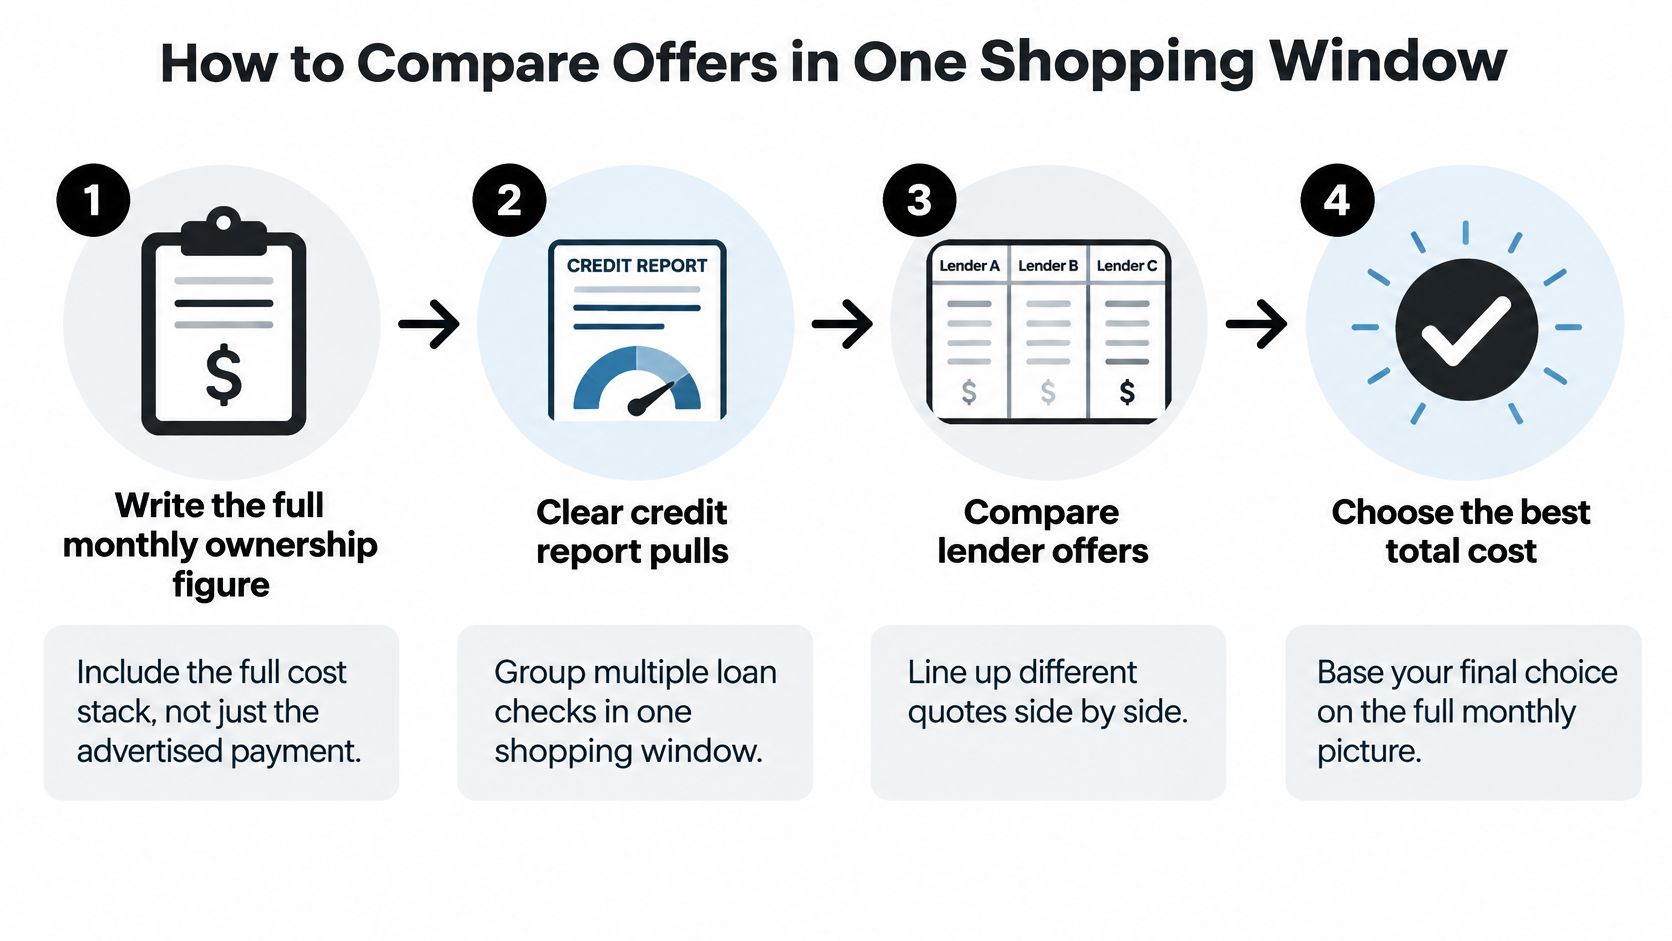
- Write your full monthly ownership figure first. Use the completed cost stack, not an advertised payment. That number is the ceiling every quote has to clear before storage, insurance, and mountain-season costs squeeze the household.
- Clear credit report errors before the first application. Every lender prices the same file, so one error can raise several quotes at once.
- Request written preapprovals inside one short window. Ask a bank, a credit union, and the dealership. The Consumer Financial Protection Bureau guidance on shopping for an auto loan says multiple auto-loan inquiries generally count as one inquiry when made within a 14 to 45 day window, and that comparison shopping may save hundreds or thousands of dollars over the loan's life. Skipping extra applications to protect your score can cost more than the inquiry.
- Fill in the worksheet for each offer. Same fields, same RV, same down payment. Fee-loaded quotes get exposed, which is why it helps to understand how fees affect personal loan APR before you assume a lower rate means a cheaper loan.
- Confirm the collateral details. Verify the unit's age, mileage or prior use, condition, and title status. Ask directly whether a tighter loan-to-value limit applies to a used or specialized toy hauler or fifth wheel.
- Take the best outside offer back to the dealer. Ask for a match on the written terms, not on payment alone. Treat our no-commitment pre-qualification as one more row on the worksheet once outside quotes exist.
- Sign only when the disclosure matches the winning quote. Check the Truth in Lending disclosure field by field, including the first-payment date.
| Line item | Offer 1 | Offer 2 | Offer 3 |
|---|---|---|---|
| APR | Written APR from lender | Written APR from lender | Written APR from lender |
| Amount financed | Dollars financed after cash down and trade | Dollars financed after cash down and trade | Dollars financed after cash down and trade |
| Term in months | Number of scheduled payments | Number of scheduled payments | Number of scheduled payments |
| Required down payment | Cash due at signing | Cash due at signing | Cash due at signing |
| Origination or documentation fees | Fees charged at signing, in dollars | Fees charged at signing, in dollars | Fees charged at signing, in dollars |
| Prepayment terms | Penalty yes or no, plus the trigger | Penalty yes or no, plus the trigger | Penalty yes or no, plus the trigger |
| Tax, title, or add-ons inside amount financed | Each item and its dollar cost | Each item and its dollar cost | Each item and its dollar cost |
| Finance charge | Total borrowing cost in dollars | Total borrowing cost in dollars | Total borrowing cost in dollars |
| Total of payments | Sum of all scheduled payments | Sum of all scheduled payments | Sum of all scheduled payments |
If a lender will not give you a field in writing, mark that row missing and treat the offer as incomplete. Verbal quotes do not survive the finance office.
The worksheet is the point. A fast approval with blanks is still a guess, while a slower quote with every field filled in can be compared, challenged, and kept.
Choose the Offer You Can Still Afford
An easy RV loan has one defining trait: you can compare it line by line and still afford it after Utah ownership costs. Keep the written offer that wins on APR and total of payments while leaving the cost stack and your reserve inside take-home pay. If the numbers work only by trimming the reserve, that offer fails.
That standard is strict for a reason. An RV you have to sell mid-season at a loss costs more than a lower-priced unit you can keep through the bad months.
| Pitfall | What it does | Better move |
|---|---|---|
| Negative equity rolled in | Finances more than the next RV is worth | Get the payoff and trade value in writing before comparing loans |
| Financed accessories | Adds years of interest on gear | Pay cash for items you will use this season |
| Advertised rate treated as yours | Hides how credit, term, and new versus used condition change the quote | Compare written APR and total of payments on the same unit |
| Term stretched to hit a payment | Balance can fall slower than the RV's value | Shorten the term or buy a lower-priced RV |
A trade can hide a weak loan. Get its value in writing, then ask plainly whether any payoff balance is being rolled into the new amount financed. Use our Value My Trade option to value a trade-in. We make cash offers on RVs customers want to sell or trade in, so you can judge the trade separately from the financing. You can also make an offer on an RV and get pre-qualified through our website before you visit.
Run your own numbers before a lender runs your credit. Our RV loan calculator guide for Utah buyers shows how price, down payment, trade value, rate, and term change the payment.
The Four Beats, In Order
Price the term on the same RV, down payment, and amount financed. Shop the written offers inside one window. Send complete paperwork so every lender prices the same borrower. Then add the payment to your Utah cost stack and reserve, and test the total against a bad month rather than a good one.
Keep-or-walk rule: If the payment only works after you cut the reserve, skip the storage line, or assume perfect seasonal income, walk away and buy smaller.
For a side-by-side quote on the same worksheet, visit our Millcreek or Spanish Fork showroom, or contact our team. Bring your outside quotes. We'll start from APR and total of payments, show you where our offer sits, and let the worksheet decide. Browse current inventory at motorsportsland.com, and plan pre-trip service through our team once you own the unit. No pressure, just numbers.
Easy RV Loan Questions Answered
Can I Get an Easy RV Loan With a Lower Credit Score
Possibly. Some secured RV programs publish no fixed minimum score, but lenders also weigh credit history, income, debt-to-income ratio, assets, and down payment. Ask for written terms instead of guessing from your score alone.
Will Several RV Loan Applications Hurt My Credit
Multiple auto-loan inquiries generally count as one when made within a 14 to 45 day window. Group your applications, get written preapprovals, and compare them before the window closes.
Is Pre-Qualification a Commitment
No. Pre-qualification is for shopping and exploring what you can afford. A full credit application is the step you take when you're ready to buy a specific RV.
Should I Finance Taxes, Title, or Warranties
Financing them raises your balance and total interest. Pay in cash when you can, unless you want the product and the offer still wins on APR and total of payments.
Can I Finance a Used RV
Yes. Expect tighter loan-to-value limits and closer checks on age, condition, and title status than you'd see on a comparable new unit.
When Does My First Payment Start
Your signed contract sets the date. Confirm it before you sign, set autopay right away, and keep a backup account funded.
Bring your completed worksheet and outside quotes to Motor Sportsland and we'll compare our written offer on APR and total of payments, value your trade separately, and help you pick a trailer, fifth wheel, or motorhome your full Utah budget can support.
